They can name every character in a Marvel franchise but can’t tell you what an APR is. They’ve survived eighteen years under your roof, eaten your food, burned through your electricity, and somehow arrived at the doorstep of adulthood believing money is an infinite resource controlled by a mysterious rectangle in your back pocket. Now they’re leaving. And they’re about to learn the hard way, unless you teach them the easy way first.
Your kid needs a long-term financial game plan beyond putting money on the big game at a top-tier trusted online sportsbook. They need to learn how to budget from you. Not the university, a YouTube guru, their roommate from Florida who “trades crypto.” You. The college budgeting conversation is the single most overlooked piece of move-in prep, and skipping it almost always ends the same way. A phone call in October. A shaky voice. “So… my account is negative.”
Your Kid Is Leaving for College – These 10 Budgeting Rules Could Save Them From Going Broke by October
This is not another sterile checklist from a parenting blog that’s never had to explain overdraft fees to a crying teenager. This is a field manual. Ten concrete budgeting tips, told straight, that will give your college-bound kid the financial vocabulary and the spending discipline to survive freshman year without a bailout. We cover the boring stuff (meal plans, bank accounts) and the stuff nobody else will touch (yes, including the night their roommate says, “Let’s throw twenty bucks on the game”). Because the conversation you have at your kitchen table in July is worth a hundred times more than the crisis you manage over the phone in November.
Let’s get into it.
Tip 1: Make the Money Talk an Actual Conversation, Not a Lecture
Most parents blow this on the first play. They sit the kid down, pull out a spreadsheet, and deliver a forty-five-minute monologue about fiscal responsibility while their teenager mentally leaves the solar system. Don’t do that.
Start by asking a question. A real one. “What do you think you’ll spend money on every week?” Then shut up and listen. You’ll learn more about your kid’s financial blind spots in five minutes of listening than you will in an hour of talking.
The goal here isn’t to scare them or to dump the full weight of adult financial anxiety onto an eighteen-year-old. The goal is to open a channel. Financial planning for college students begins with trust, and trust starts the second your kid feels like they’re part of the conversation instead of being talked at.
Frame it like this: “I’m not trying to control your money. I’m trying to help you not run out of it by October.” That sentence alone can disarm a defensive teenager faster than any PowerPoint ever will.
One more thing. Pick the right setting. Not in the car. Not five minutes before their friends arrive. At the table, with food, with your phone face down. Treat it like the serious conversation it is. Because it is one.
Tip 2: Build a Real Budget Together (On Paper, Not in Theory)
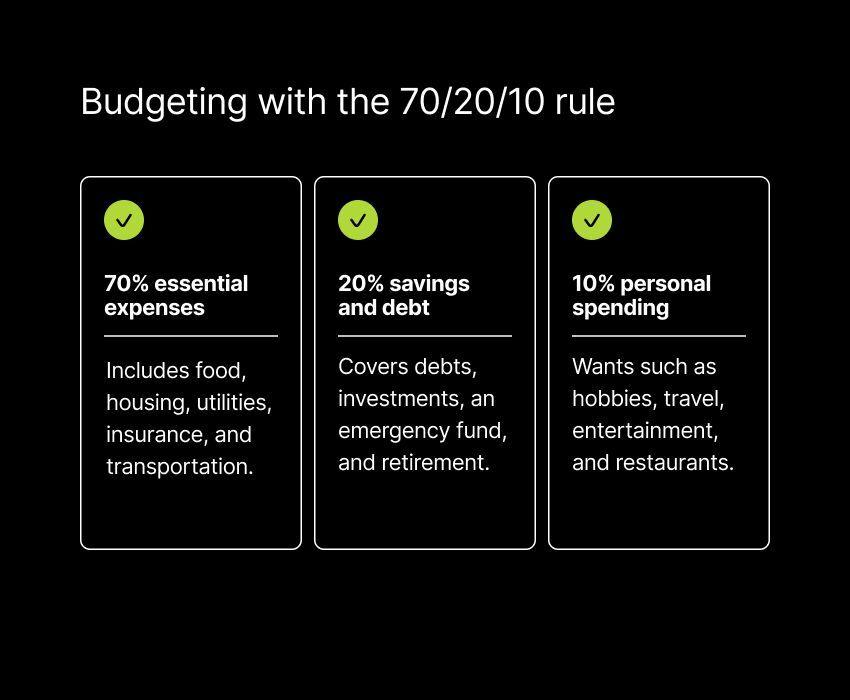
Theory is worthless. A budget only means something when the numbers are real and written down where your kid can see them.
Sit together and break their monthly finances into three buckets:
- Fixed costs: Rent (if off-campus), phone bill, insurance, any recurring payment that hits the same day every month.
- Variable costs: Food beyond the meal plan, gas or rideshare, toiletries, laundry. The stuff that shifts week to week.
- The “Oh God, What Happened” fund: We’ll get to this one later. Just know it needs its own line.
Here’s a sample monthly college budget to start the conversation:
- Meal plan top-off / groceries: $150
- Transportation: $75
- Phone bill: $50
- Entertainment: $100
- Personal care / supplies: $40
- Savings / emergency buffer: $50
- Total: roughly $465/month
Your kid’s numbers will look different. That’s fine. The point is that they see the total, feel the weight of it, and start tracking where their dollars actually go. Budgeting apps like Mint alternatives, YNAB, or even a shared Google Sheet can help, but the tool matters less than the habit. Get them to log every purchase for one week before school starts. Just seven days. The shock alone is worth the exercise.
Teach your kids about money before they leave. Not after.
Tip 3: Decode the Meal Plan Before You Overpay
The university meal plan is one of the great upsells of modern higher education. Schools will present you with a tiered menu of options designed to make the most expensive one look like the obvious choice. It is not.
Ask these questions before you commit:
- How many meals per week does your kid actually eat on campus? If they skip breakfast (and they will), that’s five meals a week you’re paying for and not using.
- Do unused swipes roll over? At most schools, the answer is no. They vanish. Poof. Gone like tuition dollars into a stadium renovation fund.
- What’s the difference between swipes and dining dollars? Swipes are locked to dining halls. Dining dollars work at campus cafes and sometimes off-campus partners. Dining dollars are almost always the better deal for students who eat irregularly.
Talk to current students or check Reddit threads for your kid’s specific school. Real intel from people who’ve lived through the meal plan is worth more than anything in the orientation packet.
Start with the mid-tier plan. You can always upgrade. You almost never get a refund for downgrading. Trim the meal plan fat and redirect those savings into a grocery budget instead. A kid who can make pasta and scrambled eggs will outlast one who depends on the dining hall closing at 8 p.m.
Tip 4: Set Up a Student Bank Account That Doesn’t Punish Them for Being 18
Your kid needs their own checking account. Not a savings account tethered to yours. Not a prepaid card. A real checking account with a debit card, mobile deposit, and zero monthly maintenance fees.
Hunt for student-specific accounts. Most major banks and plenty of credit unions offer them. The features that matter:
- No minimum balance requirement. Because their balance will hit $11.34 at some point. That’s just reality.
- No overdraft fees, or overdraft protection that actually protects. One $35 overdraft fee on a $4.50 coffee is the kind of financial gut-punch that teaches the wrong lesson.
- A solid mobile app. If they can’t check their balance in three seconds on their phone, they won’t check it at all.
- ATM access near campus. Out-of-network ATM fees are a silent tax on laziness. Make sure they have fee-free access nearby.
This is also the moment to talk about what a bank account is and what it isn’t. It’s not a score, not a game, the infrastructure their entire financial life runs on. Treat the setup process as a teaching moment. Walk them through the app. Show them how to read a transaction history. Explain what “pending” means. Small stuff, massive payoff.
Tip 5: Teach the Difference Between a Credit Card and a Debit Card Before the Campus Rep Does
Welcome Week is a minefield. Between the free t-shirts and the club sign-ups, there will be a folding table with a smiling rep handing out credit card applications like candy. Your kid needs to know the difference before that moment arrives.
A debit card spends money you have. When it’s gone, it’s gone. Simple.
A credit card spends money you don’t have. And if you don’t pay the full balance every month, interest starts compounding. Fast. A $200 bar tab at 22% APR becomes $244 in a year if they only make minimum payments. That math gets uglier by the semester.
Here’s the play: if your kid is responsible enough, a student credit card with a low limit ($300 to $500) can be a powerful tool for building credit early. But only if they treat it like a debit card. Charge small. Pay it off. Every single month.
If they’re not ready for that discipline? No card. No exceptions. A credit card in the hands of an impulsive freshman is a loaded financial weapon. There is no shame in waiting a year.
Sit them down. Explain APR in plain language. Show them a compound interest calculator. Let the numbers do the scaring for you.
Tip 6: Create an Entertainment Budget That Lives in the Real World
This is where most college budgets go to die. Not on rent. Not on textbooks. On the slow, invisible bleed of entertainment spending that never looks like much in the moment but adds up to a catastrophe by midterms.
Your kid is going to spend money on fun. Accept that now. The goal is not to eliminate entertainment expenses. The goal is to put a fence around them.
Start by naming the categories out loud:
- Streaming subscriptions. They’ll want their own Netflix, Spotify, maybe a gaming service. Individually small. Collectively, a monthly drain.
- Going out. Coffee runs, late-night food, campus events, weekend trips. This is the category that balloons without anyone noticing.
- Hobbies and social spending. Concerts, intramural fees, club dues, the random Target run that somehow costs $87.
Set a hard weekly cap. Not monthly. Weekly. A monthly entertainment budget of $100 sounds manageable until it’s October 9th and they’ve already spent $94. Weekly caps of $25 force the discipline into seven-day cycles, which is how college kids actually think about time.
Sports Betting on Campus: The Conversation You Can’t Skip
Now for the part nobody else will write about.
Legal sports betting is a fact of campus life in 2026. The apps are on their phones. The ads are on their feeds. Their friends are placing parlays on Saturday football like it’s a group activity. Because, increasingly, it is.
You can pretend this doesn’t exist, or you can prepare your kid to handle it.
If your college student is of legal age and in a state where sports betting is permitted, they may dabble. Telling them “just don’t” is about as effective as it’s ever been with any vice in human history. Instead, treat it like any other entertainment line item.
Here’s the framework:
- Assign it a fixed amount from the entertainment budget. Not extra money. Money that comes out of the existing entertainment pool. Twenty dollars a week on bets means twenty fewer dollars for concerts or eating out. Make the trade-off visible.
- Never use rent money, grocery money, or emergency funds. This is a non-negotiable wall. Entertainment cash only. When it’s gone, it’s gone until next week.
- Set deposit limits inside the app. Every major legal sportsbook has built-in tools for weekly deposit caps and loss limits. Show your kid how to set them. Then verify they did.
- Talk about the math. The house always has an edge. Always. Sports betting is entertainment with a cost, the same way a movie ticket is entertainment with a cost. The difference is that a movie ticket doesn’t pretend you might triple your money.
This isn’t about moralizing. It’s about teaching your kid to budget for the real world they’re about to walk into. A kid who understands that a $20 bet is an entertainment expense, not an investment strategy, is a kid who’s far less likely to chase losses at 2 a.m. on a Tuesday.
Tip 7: Textbooks Are a Racket. Teach Them to Fight Back.
The campus bookstore wants $189 for a psychology textbook that the professor assigned but will reference exactly twice. Don’t let your kid walk into that trap.
Teach them the hierarchy:
- Check if a free PDF exists. Library Genesis, OpenStax, the professor’s own course page. Seriously, ask the professor. Many of them know the textbook is overpriced and will point students toward free alternatives.
- Rent before you buy. Amazon, Chegg, and campus rental programs can cut the cost by 60% or more.
- Buy used. Older editions are almost always identical in content. A $30 used copy of the 5th edition beats a $180 new copy of the 6th edition that changed fourteen page numbers and a cover photo.
- Split with a classmate. One shared copy between two students who coordinate study schedules. It works more often than you’d think.
The textbook racket is one of the few areas where being cheap is genuinely the smartest move. Arm your kid with these options before the bookstore gets their claws in.
Budget the savings into something that actually matters. Like food.
Tip 8: The Emergency Fund Isn’t Optional
This is the tip that separates a plan from a prayer.
Stuff goes wrong in college. Laptops break. Cars die. A kid gets sick and needs an urgent care visit with a $75 copay they didn’t see coming. These moments are not hypothetical. They are guaranteed. The only question is whether your student has a financial cushion or has to call you in a panic.
Start small. Two hundred dollars in a separate savings account that they do not touch unless it’s a genuine emergency. Not a concert. Not a “really good deal” on sneakers. An actual, unexpected expense that can’t wait.
Here’s how to frame it: “This money is boring on purpose. It sits there doing nothing until the day you desperately need it. And on that day, it’s the most important money you have.”
If they tap the fund, the next priority is refilling it. Even if that means $20 a month. The habit of rebuilding the buffer matters more than the dollar amount.
An emergency fund won’t prevent the crisis. But it will prevent the crisis from becoming a financial catastrophe. And it’ll prevent that panicked phone call that every parent dreads.
Tip 9: Subscriptions Are the Silent Budget Killer
Here’s a fun exercise. Have your kid open their phone and list every subscription they’re currently paying for. Then add them up.
Netflix. Spotify. iCloud storage. A gaming subscription. That fitness app they used once in January. The meal kit trial they forgot to cancel.
A conservative estimate? Somewhere between $40 and $80 a month, bleeding out silently like a slow leak in a tire. That’s $480 to $960 a year spent on things they barely remember signing up for.
The fix is simple. One monthly audit. Five minutes. Go through the bank statement, highlight every recurring charge, and ask one question per line: “Did I actually use this in the last 30 days?”
If the answer is no, cancel it. Today. Not “after this billing cycle.” Today.
Share family plans where it makes sense. Spotify Family, YouTube Premium family, cloud storage bundles. The savings add up fast when you stop paying for five individual subscriptions that one family plan covers.
Kill the subscriptions. Reclaim the cash. Redirect it toward something they’ll actually use.
Tip 10: Check In Without Checking Up
You’ve done the work, had the conversation, helped build the budget and set up the accounts and talked through every scenario from meal plans to emergency funds. Now comes the hard part.
Letting go. Partially.
Your kid needs space to make financial decisions on their own, including the bad ones. A $14 impulse buy at a campus convenience store is not a crisis. It’s a lesson. The urge to monitor every transaction and call out every misstep will backfire. Fast.
Instead, schedule a low-pressure monthly check-in. Frame it around curiosity, not control. Try these:
- “What surprised you most about your spending this month?”
- “Anything you wish you’d budgeted differently?”
- “Do you feel like your entertainment budget is working, or does it need adjusting?”
These questions keep the door open without kicking it down. They respect your kid’s autonomy while maintaining the connection. And they reinforce the core idea that money is something you talk about openly in this family, not something you hide until it becomes a problem.
That’s what Talk & Play has always been about. Communication. Not control. The financial version of that principle is the same. Stay in the conversation. Trust the preparation. And when they stumble (they will), be the person who helps them figure it out, not the person who says, “I told you so.”
The Bottom Line
Teaching your kid to budget before college is not about spreadsheets. It’s not about control. It’s about giving them a language for money that they’ll carry for the rest of their lives.
The ten conversations above won’t prevent every mistake. They aren’t supposed to. But they will build a foundation strong enough that when the mistakes come, and they will come, your kid has the tools to recover without spiraling.
Start this week. Pick one tip. Sit down at the table. Open the conversation. You don’t need to cover everything in one sitting. You just need to start.
Because the parent who talks about money openly raises the kid who manages it wisely. And that, more than any meal plan or bank account or budgeting app, is the thing that actually lasts.
Frequently Asked Questions
How much spending money does a college freshman actually need per month?
It depends on the school and the city, but a reasonable range is $400 to $600 per month for a student with a meal plan already covered. That number should include food beyond the dining hall, transportation, personal supplies, entertainment, and a small emergency buffer. Sit down together and build the number based on real local costs, not national averages.
What’s the best way to set up a college budget for the first time?
Start with income (parental support, part-time job, financial aid refund, savings) at the top of a sheet. List every known monthly expense below it. Subtract. If the number is negative, you’re not done yet. Use a budgeting app or a shared spreadsheet, but the format is less important than the act of writing it all down and reviewing it weekly.
How do I talk to my college student about sports betting without starting a fight?
Lead with curiosity instead of judgment. Ask what their friends are doing. Ask if they’ve seen the ads on campus. Then frame sports betting the same way you’d frame any other form of paid entertainment: it has a cost, it needs a limit, and it should never come from money earmarked for necessities. The calmer you are, the more they’ll actually hear you.
Should I give my college kid a credit card?
Only if they’ve demonstrated they understand how credit works. A student card with a $300 to $500 limit can help build their credit history early, but only if they pay the full balance every single month. If there’s any doubt about their discipline, start with a debit card and revisit the credit conversation after the first semester.
How often should I check in on my kid’s finances after they leave for school?
Once a month is the sweet spot. Enough to stay connected and catch problems early, not so often that it feels like surveillance. Ask open-ended questions about what surprised them or what they’d change. Keep it collaborative, not confrontational. The goal is a lifelong habit of talking about money, not a semester-long audit.